All Categories
Featured
Financial Planning for Elder Care in 2026
Table of Contents
Does Medicare cover long-term care? Initial Medicare does not pay for custodial care, which is assistance with everyday activities like bathing, dressing, or using the bathroom. Many individuals who require long-lasting care require non-medical aid.
Despite our attempts to make this website accessible for everybody, there may still be some pages or sections that are not entirely accessible, are in the process of becoming available, or do not have an appropriate technological service to make them available. We are always making every effort to boost our availability by adding, updating, enhancing its options and functions, and including new technologies.
If you want to call this site's owner, please use the contact kind on the website. - With this tool, users can customize font size, style, letter spacing, and line height for enhanced positioning and readability. - Users can customize their color contrast profiles to light, dark, desaturated, and monochrome.
- Users can allow focus mode to highlight the current page details based on their mouse motion.
One of the most typical and pricey misconceptions in retirement preparation is the presumption that Medicare will pay for long-lasting care. Medicare is a federal health insurance coverage program for individuals age 65 and older, and for specific more youthful individuals with disabilities.
Understanding Long-Term Care Insurance Versus Medicare
Short-term skilled care after a qualifying healthcare facility stay of at least 3 days. Medicare was not designed to pay for the ongoing custodial care that a lot of long-term care claims include.
Whether the care is delivered at home, in an assisted living community, in memory care, or in a knowledgeable nursing center, Medicare will not money it once the short-term skilled window closes. Two words bring a great deal of weight in this area: and. care is what a certified clinician supplies: injury care, IV treatment, physical rehabilitation.
Retirement Planning Rancho Cucamonga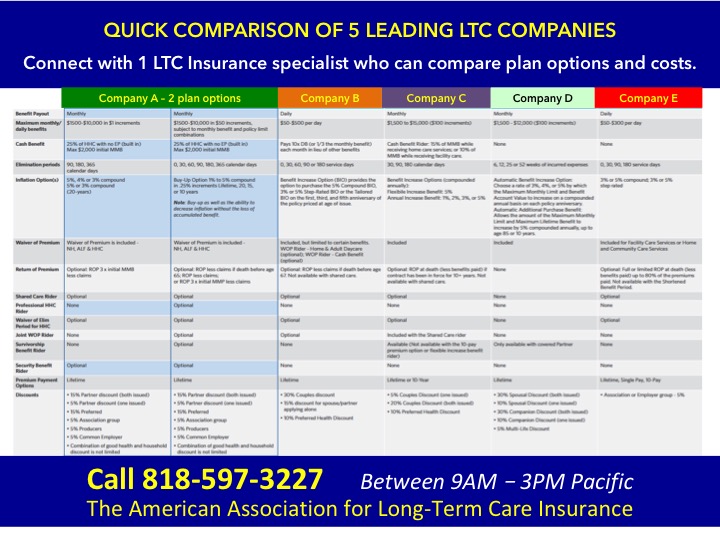
care is the continuous assistance with day-to-day living that many long-term care really is. Medicare does not cover this. When the short-term skilled window closes and care continues, the costs moves entirely to the household (or, in many cases, Medicaid after properties have actually been spent down). Long-Term Care Insurance coverage was developed specifically for this custodial care.
Numerous agreements likewise consist of care coordination services that help a household navigate providers and paperwork. Believe of it in this manner: Medicare covers the medical side (hospital, doctor, short-term rehabilitation). Long-Term Care Insurance coverage covers the daily-living side once the medical piece is done. Both belong in a real retirement plan; they do different jobs.
Protecting Your Savings With Accident Policies
Partnership-qualified Long-Term Care policies, available in many states, supply extra Medicaid property defense if advantages are ever exhausted. If your retirement strategy assumes Medicare will deal with a long-lasting care occasion, it does not.
Assuming Medicare will get the job done is the plan that fails. Prepared to talk it through? A short conversation is the fastest way to see whether the ideas here fit your situation. Keep reading U.S. Department of Health and Person Services, (care statistics and meanings). Genworth Expense of Care Survey (annual market expense benchmark).
National Association of Insurance Commissioners, A Consumer's Guide to Long-Term Care Insurance Coverage. Illustrative pricing in this post is for education only and does not represent a quote for any specific person or policy.
Have you considered how you would desire to receive care if you can't care for yourself in the future? Have you prepared to pay for it?
Closing the Shortfalls in Traditional Coverage
Comprehending the difference in between Short-term Care insurance vs. Long-term Care insurance coverage can assist you produce a care plan that ensures your finances are well secured. Long-lasting Care insurance coverage helps cover the assistance that you'll need when you can no longer carry out jobs by yourself from chronic disease, special needs, and/or problems.

Latest Posts
Critical Illness Coverage for Older Americans
Financial Planning for Elder Care in 2026

Planning for 2026 Care Fees in the US