All Categories
Featured

Severe Illness Protection for Seniors
Table of Contents
Comparison of Linked-Benefit vs. Conventional LTCi - Long-term care protection has actually evolved substantially. An independent expert can side-by-side compare conventional LTC policies against hybrid/linked-benefit alternatives (like combination life insurance or annuity LTC policies) to see which structure fits your financial goals. Professional Navigation of Health Underwriting - Medical underwriting standards for long-lasting care insurance coverage vary widely in between providers.
Retirement Planning Santa Ana CAConsiderable Cost Cost Savings - Rates for comparable long-term care benefits can vary by 30% to 80% or more in between insurance provider. An independent broker compares rates across the board to guarantee you do not overpay for your coverage. Custom-made Policy Design - Long-term care policies aren't one-size-fits-all. An expert helps customize key policy leverssuch as monthly advantage quantities, advantage durations, removal (waiting) durations, and inflation security ridersto fit your precise budget and care preferences.
An independent representative comprehends how to structure policies to fulfill state-specific Partnership requirements. Discounts & Shared Care Options - Specialists understand how to take full advantage of available cost savings, such as spousal/partner discounts, preferred health discount rates, and "shared care" riders that enable couples to draw from a combined swimming pool of advantages. Structured Application & Underwriting Process - Making an application for LTC protection involves medical records reviews, phone interviews, and in some cases cognitive screenings.
Advocacy at Claim Time - An independent professional's job doesn't end when the policy is provided. When care is ultimately required, they work as an educated advocate for you and your household, helping browse claims, documents, and benefit triggers. "The number of various long-lasting care insurer are you certified to represent?" Why ask: Ensures they are genuinely independent and capable of using a detailed market contrast rather than pitching a limited choice.
"Based on my personal medical history, which carriers are more than likely to use me beneficial underwriting rates?" Why ask: Financing standards differ considerably; asking this checks the representative's knowledge of carrier-specific health requirements before you officially apply. "What inflation defense choices do you suggest for somebody my age, and how will they affect my premium in time?" Why ask: Inflation security is critical to equal increasing care expenses, but it significantly affects premiums.
Benefits of Fixed and Variable Annuity Strategies
simple inflation options perform over 10, 20, or thirty years. "Will you or your office help my household and me with suing when care is really needed in the future?" The American Association for Long-Term Care Insurance (AALTCI) is the leading national trade company and consumer advocacy group committed to long-term care planning, education, and research study.
Why AALTCI is the Market Standard Primary Source for Market Data & Stats: AALTCI conducts and publishes the yearly Long-Term Care Insurance Cost Index, the gold standard industry benchmark tracking premium costs, provider rate variations, and policy patterns throughout traditional and linked-benefit (hybrid) long-term care products. Independent & Unbiased Consumer Guidance: As a nationwide organization, AALTCI does not offer insurance directly.
Vetted Expert Network: AALTCI links individuals with certified, knowledgeable, independent long-lasting care insurance agents who represent numerous premier insurance carriers, making sure customers get tailormade alternatives without carrier predisposition. Acknowledged Thought Management: Cited often by major media outletsincluding The Wall Street Journal, The New York Times, Forbes, and Kiplinger'sAALTCI functions as the main media source for market analysis, regulatory updates, and consumer protection guidance regarding long-term care choices.
Independent Expert Matching Service A complimentary customer service that pairs buyers with credentialed, independent LTC experts certified in their specific state. Customer Shopper's Guides & Toolkits Step-by-step academic guides discussing standard LTC insurance, linked-benefit life/annuity mix strategies, state Partnership Programs, and tax-deductible premium standards. Claims & Policyholder Advocacy Info and guidance for households navigating the policy application, advantage trigger, and claim filing procedures.
How Senior Accident Insurance Secures Assets
American Association for Long-Term Care Insurance Coverage (AALTCI) Jesse Slome, Director, who has spent years in the long-lasting care insurance coverage market (considering that 1987). Jesse Slome, Director July 28, 2026 2026 AALTCI Long-Term Care Insurance Price Index.
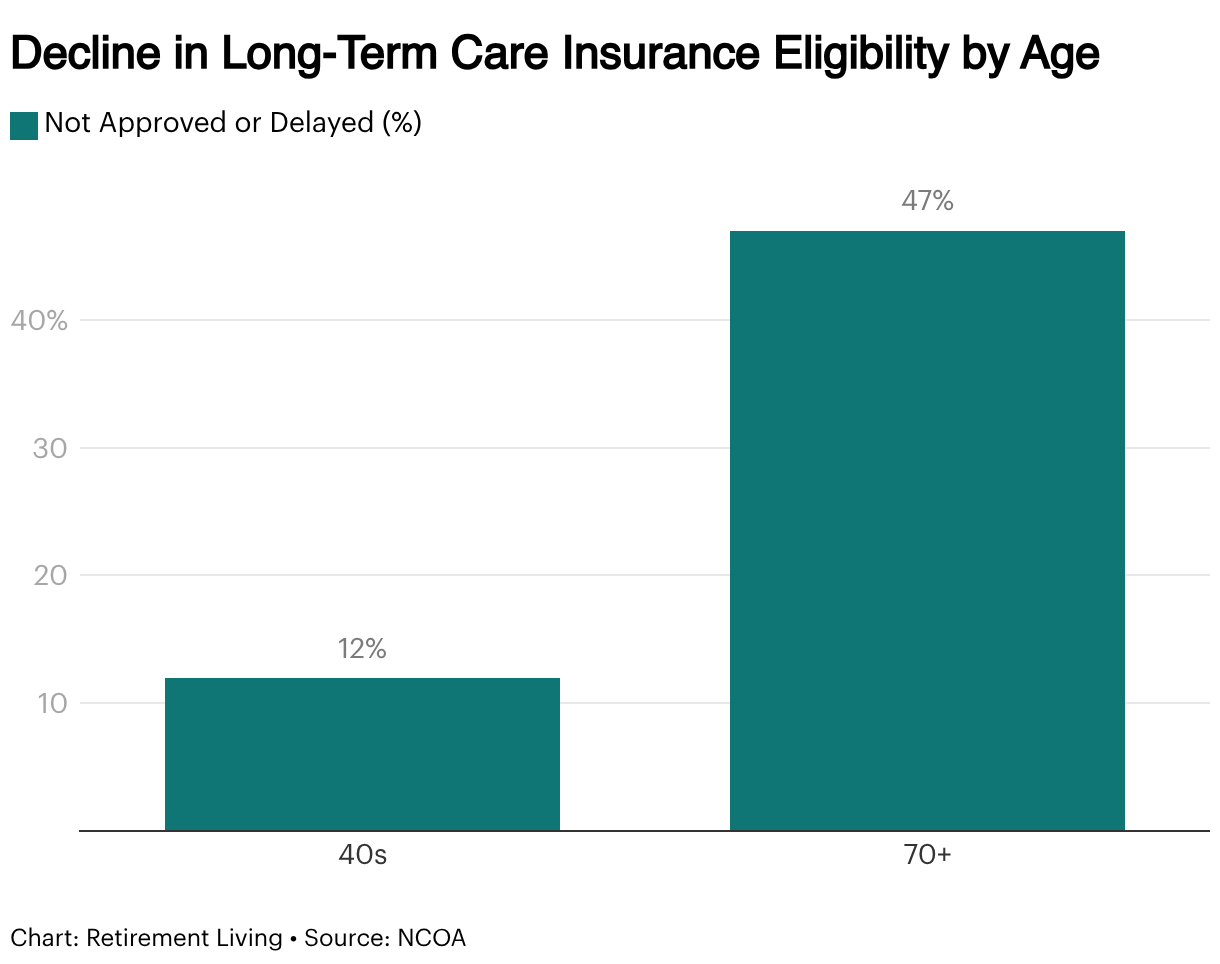
In 2026, you can expect to pay anywhere from $79 to $533 per month for a long-lasting care insurance coverage policy. These premiums, nevertheless, differ significantly based on age, gender, health, and the protection amount of the policy.
The premiums can be pricey, but they're definitely worth it for people expecting a requirement for care. Without insurance, long-lasting care costs can be extremely high.

Latest Posts
Critical Illness Coverage for Older Americans
Financial Planning for Elder Care in 2026

Planning for 2026 Care Fees in the US