All Categories
Featured
Top Advantages of Senior Accident Insurance
Table of Contents
Hybrid policies can secure both income and estate. Consist of real-life care situations: dementia, mobility loss, single-spouse requirement. In-home vs. center, household participation, care quality. Medicare is essentialbut it's not enough by itself. The best time to prepare for long-term care is when you do not need it yet. Because the peace of mind you'll have later begins with the choices you make today.
acts as the Chief Financial Investment Officer at Langan Financial Group. In this role, he handles financial investment portfolios, serves as a fiduciary for group retirement plans, and seeks advice from customers concerning their financial objectives, threat tolerance, and asset allowance. With a concentrate on ERISA Law, Alex finished cum laude from Widener Commonwealth Law School.
Alex is likewise passionate about returning to the neighborhood, and has actually taken part in The Foundation of Enhancing Neighborhoods' Emerging Benefactor Program, volunteers at his church, and acts as a board member of Samara: The Center of Person & Household Growth. Beyond work and volunteering, Alex enjoys his time with his better half Sarah, and their 3 kids, Rory, Patrick, and Ava.
Variable and Fixed Annuities for Seniors
Your household's future. Langan Financial Group offers monetary preparation and financial investment management for individuals, families, and organization owners. We help you work through concerns about retirement income, investment decisions, Social Security, and how taxes might affect your monetary plan.
From there, we help you examine your alternatives and develop a plan that can evolve as your life changes. We also assist services and organizations examine workplace retirement strategies and understand their obligations as plan sponsors.
Retirement Planning Escondido CAThe opinions revealed and material supplied are for general information, and should not be thought about a solicitation for the purchase or sale of any security.
Most Americans erroneously believe Medicare will cover their long-lasting care needs in retirement. This important misunderstanding can lead to devastating financial effects when care is ultimately required.
How to Evaluate Medicare and LTC
The relationship between long-term care (LTC) and medical care covered by TRICARE, Medicare, or employer health care can be confusing. Examples of health insurance coverage include your health insurance at work, TRICARE or TRICARE for Life, and Medicare. These cover medical expenses associated with the treatment of an illness or injury.
After treatment, recuperation or healing is not covered. It's about the need for help when you can't carry out typical activities of life and you need assist to work. LTC is upkeep, not treatment. At this moment, physician have actually done all they can, and all that's left is recovery or dealing with a disability that makes you require daily help.
Many individuals believe of LTC as nursing home care. A better description would be stay-at-home care.
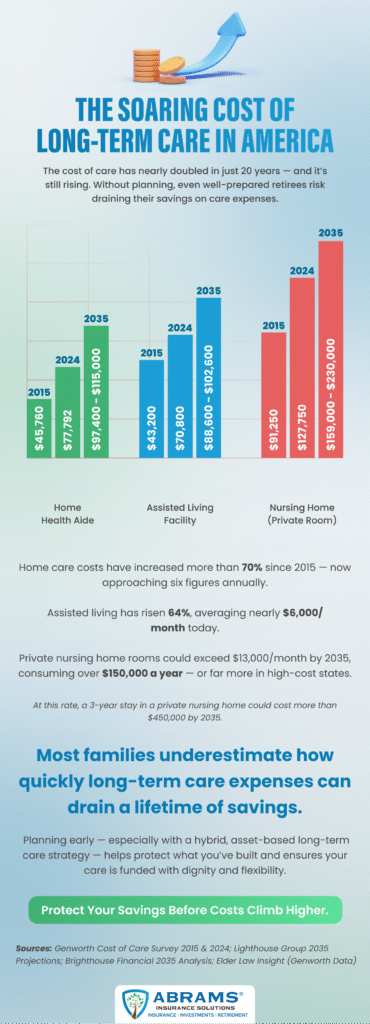
Managing Rising Care Costs in 2026
Most Americans wrongly think Medicare will cover their long-term care requirements in retirement. This vital misconception can cause ravaging financial consequences when care is ultimately required. Medicare offers restricted coverage for long-lasting care services: As much as 100 days maximum Needs a qualifying 3-day health center stay first Days 21-100 need an everyday copayment ($200+ each day in 2025) Must show continuous improvement to maintain coverage Limited protection Requires physician accreditation of medical necessity Must be experienced nursing care (not custodial) Care must be part-time or periodic only the help with activities of everyday living that Medicare does not cover:.
While it may be tough to think of now, it's most likely that you'll need some kind of health care or daily living support as you age. People typically believe that Medicare covers long-lasting care, either in the house or in a nursing facility, however unfortunately, that's not the case. Medicare does not cover assisted living, skilled nursing, or long-lasting care.
If you're not able to leave your house for medical or therapeutic care, Medicare will spend for home health care services. Importantly, Medicare will not cover 24-hour care. Long-term Care (LTC) Insurance coverage is designed to cover long-lasting services and support not covered by conventional medical insurance coverage or Medicare. It can include a variety of benefits for individuals who require continuous medical attention and/or custodial care with daily activities like consuming, bathing, or movement in centers from assisted living to full-time, in- home custodial care to a private room in a nursing center.
The expense of a long-lasting care policy is based upon age, desired advantage amount and any fringe benefits you choose to consist of. That's why it is necessary to identify your long-term care needs and level of security before it becomes an emergency. Considering long-lasting care is a cornerstone in any financial strategy, and there are many alternatives to pick from based on your monetary circumstance and needs.
Retirement Planning Escondido CALong-Term Care Alternatives Beyond Medicare
It's much better to be overprepared and covered, than underprepared and economically ravaged.
Medicare does not cover your long-lasting nursing care or 24/7 in-home services, nor does it pay for your custodial care which includes your day-to-day activities such as consuming, bathing, and dressing.
Why do numerous monetary consultants tell clients they can self-insure for long-term care however recommend them to purchase supplemental coverage to Medicare? This concern has actually plagued me for 30 years. The primary factor this subject is so important is that the most typical objection my group and I encounter relating to long-term care insurance coverage is, "I'm going to self-insure." Lots of people truly desire the protection of insurance coverage, yet their financial advisor often suggests that self-insurance is more suitable.
They regularly buy Part D drug protection, either paired with Medicare Advantage or a traditional Medicare supplement. Financial advisors seldom encourage versus buying extra Medicare coverage.
Key Advantages of Senior Accident Insurance
The typical claim payment is considerably less than $4,000 per year, according to Telos Actuarial. For 2026, there is a $2,100 cap on drug protection under Part D. If you do not think me that the claim payments are little, look at the Explanation of Benefits that shows the claim payments from your Medicare Supplement or Part D drug strategy.

Latest Posts
Critical Illness Coverage for Older Americans
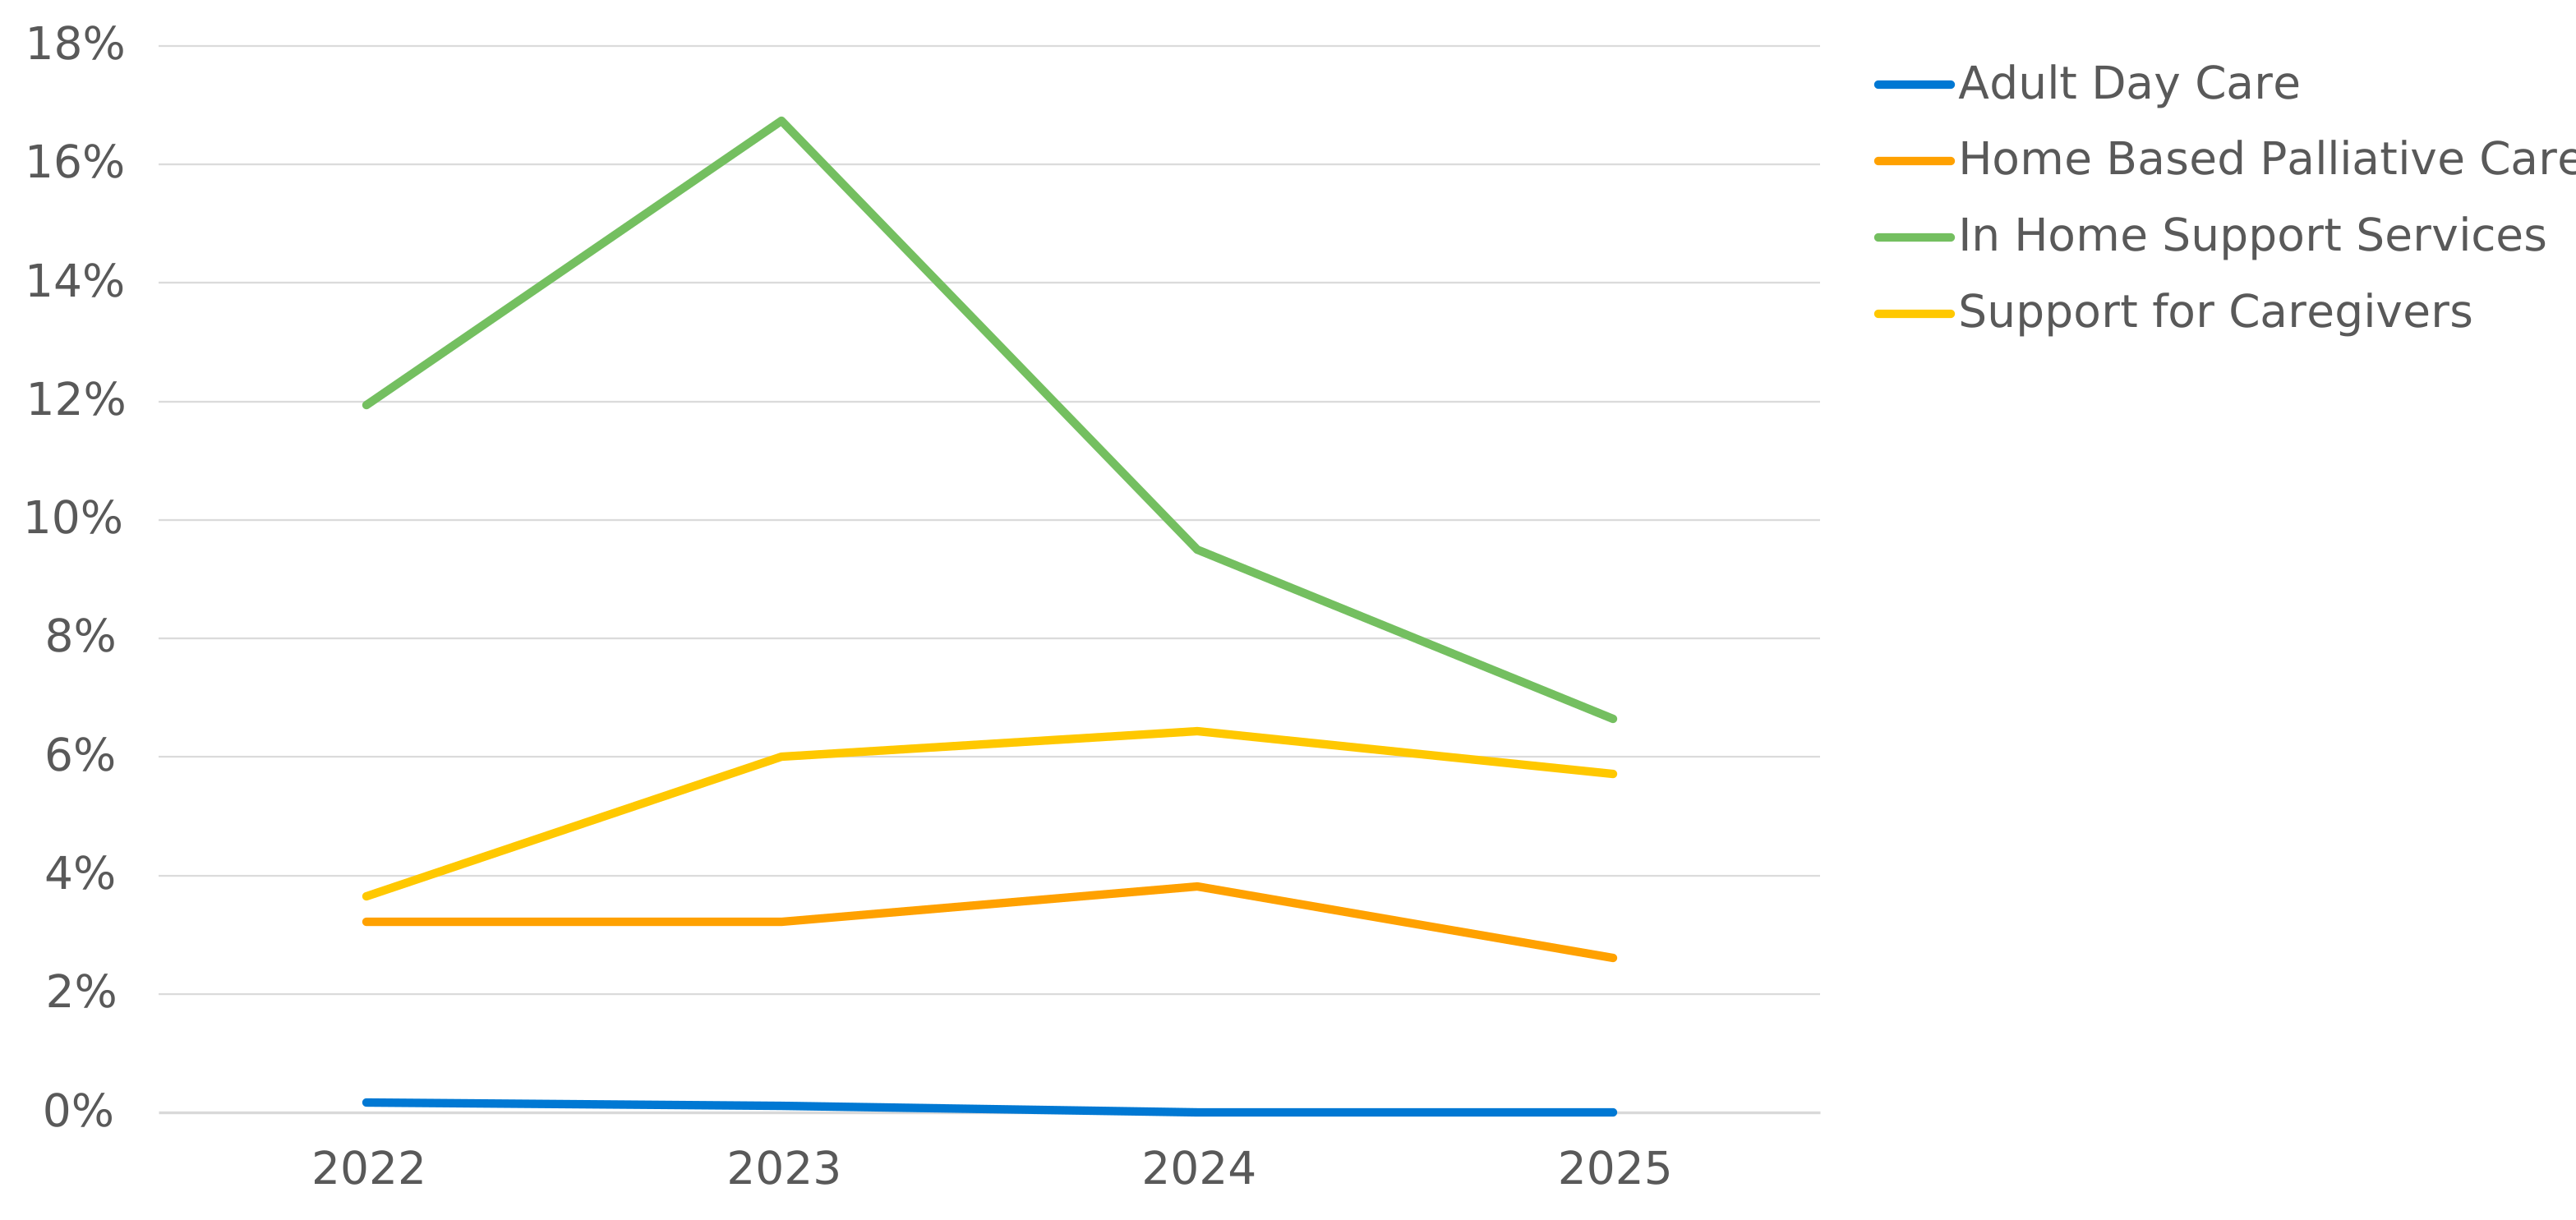
Financial Planning for Elder Care in 2026

Planning for 2026 Care Fees in the US